Limited companies have historically produced tax savings for businesses at many profit levels. However, corporation tax rose from 1 April 2023, dividend tax rates have since increased, most recently from 6 April 2026, and the dividend allowance has fallen from £2,000 to £500.
With companies and shareholders now facing higher tax costs, should associate dentists still incorporate? The answer depends on the dentist’s NHS work, profit level, personal income needs and family circumstances.
As more associates reduce or stop NHS work, trading through a limited company remains attractive. Our assessment covers:
- Will the dentist be carrying out NHS dental services? If so, are they happy to stop contributing to the NHS Pension Scheme and also lose out on NHS parental pay benefits? Or can this be split?
- Is the profit level sufficient to make the limited company worthwhile?
- How much income do they require each month for their personal living expenses?
- Does the dentist have a spouse who could be a minority shareholder in the company?
NHS Dentistry
A dentist providing NHS treatment through a limited company becomes ineligible to make NHS pension contributions from the date company trading begins. Dentists currently contributing should obtain independent financial advice because the lost pension benefits can be significant, particularly where NHS work is substantial.
Incorporation can also mean losing NHS parental-leave benefits, which are based on estimated net pensionable earnings: two weeks for men and 26 weeks for women. For example, a woman with annual net pensionable earnings of £50,000 could receive £25,000. Dentists planning children should weigh this loss before incorporating.
The NHS income can remain out side of the company but this does reduce potential tax savings and comes with additional admin and costs.
Annual Profits
Expected profits matter. Below £50,270, tax savings may not offset the extra company-accountancy costs, and planning opportunities are more limited than for a higher-rate taxpayer. Very profitable dentists may also save little or nothing if they withdraw all post-corporation-tax profits for personal spending.
At several profit levels, especially higher ones, the combined corporation tax and personal tax can exceed the effective tax rate for self-employment. Dentists needing all company income may therefore gain no tax saving unless a lower-income spouse can hold shares. By contrast, retaining some post-tax profit gives greater control over personal income and can save or defer tax.
Income Required From The Company
A company pays corporation tax on its profits. Post-tax profits become retained earnings or reserves, from which dividends may be paid when sufficient reserves exist. The company need not distribute all reserves each year; cash can remain because:
- Shareholders need fewer dividends for personal spending.
- The company is building funds for capital expenditure, a practice or property purchase.
- The director expects to reduce working hours, for example during parental leave, and wants reserves to support dividends while profits fall.
- A dentist approaching retirement wants a later income source or plans, with advice, to dissolve or liquidate the company. Business Asset Disposal Relief may reduce Capital Gains Tax on a qualifying distribution.
Taking less income lowers shareholders’ personal tax. With marginal dividend rates potentially 35.75% or 39.35%, leaving unneeded cash in the company can create significant tax savings or deferral.
For profits above £100,000, a company can help keep adjusted personal income at or below £100,000. This preserves the personal allowance, which is withdrawn between £100,000 and £125,140 and can create an effective tax rate of up to 60%, and can also preserve eligibility for tax-free childcare.
Other Shareholders
A spouse may be a minority shareholder. If they receive no other dividends, £500 can be paid without income tax. If their income is below £50,270, dividends above £500 can bring it up to that level at 10.75%, rather than the dentist potentially paying 35.75% or 39.35%.
Even where the spouse earns above £50,270, allocating dividends to them may still help if the dentist would otherwise exceed £100,000 and lose personal allowance.
Not A One Size Fits All Solution
Incorporation is not a one-size-fits-all solution. At DJH, we assess each dentist’s NHS benefits, profits, income requirements, family circumstances and future plans before recommending a trading structure.
If you are considering incorporating your associate dentist business, our specialist team can review every aspect and guide you through the process.
To speak to our team on how we can assist, give us a call.
This article was revised ahead of the Autumn Budget on 28 October 2026, which may introduce further changes to dividend tax, Capital Gains Tax, or company profit extraction. If you are reading this after that date, check nothing has moved on before relying on it.
Enter your details above to receive a link you can use to download your FREE pdf
Read More
Here's What New Associates Need To Know
What Is Your Definition Of Retirement?
How Often Do You Look Back On Your Life And Think “I Wish That I Knew Than What I Know Now?”
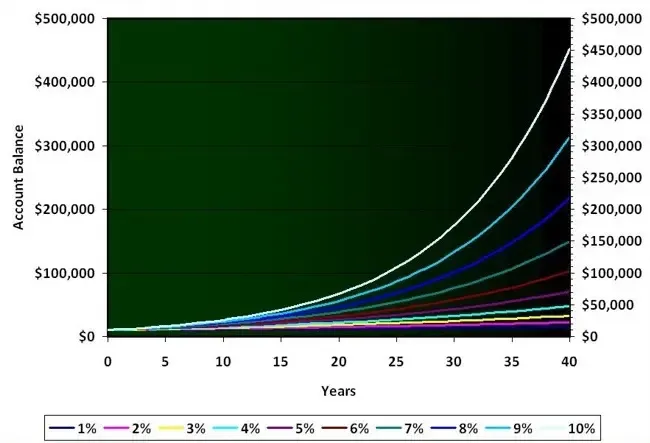
Can I Invest In My ISA For Passive Income?
The Role Of Luck In Investing
DENTISTS WHO INVEST LIMITED IS A LIMITED COMPANY, REGISTERED IN ENGLAND AND WALES