Dental practice owners often ask whether changing from a sole trader or partnership to a limited company will save tax. Historically, companies often produced savings across a wide range of profit levels.
However, corporation tax rates rose from 1 April 2023, dividend tax rates have since increased—most recently from 6 April 2026—and the dividend tax-free allowance has fallen from £2,000 to £500.
Given these higher costs, can incorporation still save dental practices tax?
We assess incorporation against a checklist tailored to the practice owner:
- What debt does the practice have, and on what lending terms?
- Could the dentist’s spouse be a minority shareholder?
- What are the owner’s short-term (under two years) and longer-term plans?
- Are there plans to buy another practice?
- Does the owner need all practice income for personal living costs?
- Would a company offer tax-planning opportunities unavailable under the current structure?
- If incorporation is suitable, how should the practice sale to the company be structured for tax?
This is not exhaustive: each practice must be assessed individually. The following points merit closer attention.
Current Lending for the Dental Practice
Practice debt may include funding for goodwill, property and equipment hire purchase. On incorporation, the owner will usually want the company to assume these liabilities. A bank may need to issue new company loans, potentially charging arrangement fees or changing the interest rate.
This can also be an opportunity to reorganise borrowing at a lower rate. DJH’s Commercial Funding Solutions team has helped clients refinance on incorporation, consolidate loans, reduce their overall interest rate and lower monthly finance costs.
Corporation tax remains payable on company profits, reducing available cash. Dividends are then paid from that cash, and the dentist incurs income tax only on dividends actually received.
For some practices, this can produce substantial tax savings.
Spouse as a Shareholder
A sole trader is taxed personally on all business profits, so family tax planning may be limited even where their spouse earns less.
Through a limited company, the spouse may hold a minority shareholding and receive dividends instead of the dentist. This can significantly reduce annual income tax where the spouse earns below £50,270 and/or the principal dentist would otherwise have personal income above £100,000.
Family circumstances should therefore form part of every incorporation review.
Personal Income Required for the Principal Dentist
As a sole trader, practice profits are subject to income tax and National Insurance. With the additional income tax rate at 45% above £125,140, liabilities can be substantial, although the post-tax profit is then available for personal spending.
In a company, profits are subject to corporation tax and the balance becomes available reserves. The principal dentist, as director and shareholder, can decide how much to distribute as dividends.
If the dentist does not need all reserves personally, profit and cash can remain in the company for practice investment, shares, pension contributions or a deposit on a future practice. Lower personal income can also reduce income tax.
For example, a sole trader earning £200,000 would face an effective tax rate above 41%. The same practice operating through a company could have a much lower effective rate if the dentist needs only £80,000 from the company for personal spending and tax.
Accumulated company cash can also support planning for a future sale. Business Asset Disposal Relief (BADR) may still apply on a sale or liquidation, subject to its qualifying conditions and £1 million lifetime limit.
Is a Company the Right Business Structure for your Dental Practice?
Incorporation offers several tax-planning opportunities. It will not suit every practice, but careful planning can still deliver significant annual savings.
If you are considering incorporation, speak to our specialist team. We can assess annual tax planning, lending requirements and a structure tailored to your personal needs.
This article was revised ahead of the Autumn Budget on 28 October 2026, which may introduce further changes to dividend tax, Capital Gains Tax, or company profit extraction. If you are reading this after that date, check nothing below has moved on before relying on it.
Enter your details above to receive a link you can use to download your FREE pdf
Read More
Here's What New Associates Need To Know
What Is Your Definition Of Retirement?
How Often Do You Look Back On Your Life And Think “I Wish That I Knew Than What I Know Now?”
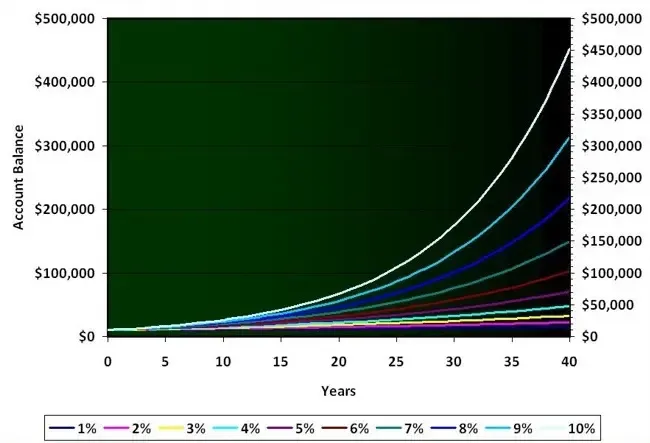
Can I Invest In My ISA For Passive Income?
The Role Of Luck In Investing
DENTISTS WHO INVEST LIMITED IS A LIMITED COMPANY, REGISTERED IN ENGLAND AND WALES